From bank lending and private debt to club deals and securitisation, Federico Lione examines why the capital structure must be designed alongside the real estate asset.
Analyses, case studies and market notes from CGPH Banque d’affaires — corporate finance and strategic advisory.
Editorial articles and news updates covering our advisory perspectives.
Video conversations and institutional presentations.
Sector guides and books published by CGPH Banque d’affaires, including From Idea to Capital.
A 15-part series by Andrea Battista LL.M. on the legal architecture of an M&A deal.
A 10-part series by Andrea Battista LL.M. on financing readiness and the advisory side of a capital raise.
Independent editorial coverage and verified press releases featuring CGPH Banque d’affaires and Altherum.
Upcoming meetings and the archive of past events.

From bank lending and private debt to club deals and securitisation, Federico Lione examines why the capital structure must be designed alongside the real estate asset.

The digital euro is often presented as a technology project. Its real significance is broader: Europe is testing whether public money can remain usable in an economy where everyday payments are increasingly digital, while improving resilience, preserving privacy and avoiding dependence on a small number of non-European payment providers.

Salesforce's agreement to acquire Braze has an intuitive strategic logic: combine a broad customer platform with real-time engagement capabilities. But product complementarity is only the opening hypothesis. The value of the transaction will depend on a more demanding question—how the two companies turn that fit into an operating model customers, product teams and shareholders can actually observe.

Private credit has grown into a USD 4.1 trillion market. Its next phase will be defined less by fundraising volume than by credit selection, structural protection and the ability to distinguish temporary pressure from impaired fundamentals.

A business can have attractive economics, a credible strategy and a capable management team—and still be difficult for investors to understand. Financial communication closes that gap only when it connects performance, cash, risk and capital needs in one coherent account.

A lower policy rate does not automatically create a reliable financing window. When sovereign-market liquidity depends increasingly on leveraged intermediaries and short-term funding, repo terms, margin calls and balance-sheet capacity can tighten before the policy story changes. For corporate borrowers, the practical question is not only where rates may go, but whether markets can absorb risk when capital is needed.

A renewed policy confirms that cover was placed for another period. It does not prove that the asset will remain insurable on acceptable terms, meet future lender requirements or preserve tenant continuity and exit liquidity. Durable financeability requires a multi-year link between physical risk, insurance structure, capital expenditure and debt.

A bridge round is not successful because it adds six or nine months of runway. It is successful when those months produce evidence that changes the company’s next financing, strategic or operating choice. Without that evidence, the bridge may simply finance another round of the same uncertainty.

Payment-in-kind interest can preserve cash when a company needs it most. But the unpaid coupon does not disappear: it becomes a larger claim on the value that must remain at refinancing, a sale or maturity. The right test is not whether PIK creates runway. It is whether the business can outrun the accretion.

Sazerac’s announced EUR 5.55 cash offer for Berentzen carries an approximately 68% premium to the cited unaffected three-month XETRA average. That is the most visible number in the transaction. It is not yet the whole decision package. The offer document, detailed conditions and the boards’ joint reasoned statement remain to be published.

Europe’s funding debate often starts with the size of household savings and ends with the financing needs of innovative companies. The distance between those two figures is not a rounding error. It is a chain of mandates, vehicles, market infrastructure, cross-border rules, investor confidence and company-level financeability.

A maturity extension can remove an immediate refinancing cliff. It does not, by itself, create cash generation, reduce leverage or prove that the next refinancing will be available. The decision is credible only when the extra time is tied to a measurable route toward a financeable capital structure.

An earn-out converts part of the price into a claim on future performance. But after closing, the buyer normally controls the decisions that shape that performance. The valuation bridge therefore works only when the metric, operating model, information rights and dispute route are designed together.

A transaction does not become ready when the data room is full. It becomes ready when the board knows what it is trying to achieve, which evidence can support the case, where the process can break—and who has authority to decide when it does.

The strongest strategic investor may bring distribution, credibility and operating leverage that financial capital cannot replicate. The same investor can also create information, governance and competitive constraints that only become visible when the next financing or exit begins.

A site is not power-ready because a megawatt figure appears in a grid letter, a marketing deck or a development model. The investment case begins when capacity, timing, resilience and contractual responsibility can be tested together.

A synthetic transaction can create regulatory-capital capacity by transferring credit risk. Whether that capacity becomes corporate lending, balance-sheet resilience or distributions is a separate decision.

The H.I.G.–MISTRAS agreement shows why a go-shop must be read with financing, voting support, termination economics and closing certainty.

Investors often spend weeks underwriting the company and hours reading the system that will govern them after closing. In a club deal, both deserve diligence: the asset creates the return, but the decision system determines how risk, information and control travel between investors.

Preferred equity can preserve cash today while moving part of its price into tomorrow’s ownership, decision rights and exit proceeds. The instrument should be judged as a system, not by the absence of a scheduled coupon.

A carve-out does not transfer the business described in the presentation. It transfers the legal entities, assets, liabilities, people, contracts and dependencies that the documents can place on one side of the line at completion.

The percentage sold is visible. The influence transferred is dispersed across board rights, reserved matters, information, future funding and exit provisions. A serious minority-capital decision prices both.

Macquarie Asset Management’s first European CLO is a useful market signal. The important question is not whether risk has vanished, but where it has moved, who now bears it and what new capacity can actually finance.

The difficult question is no longer whether rates are higher. It is whether an energy shock lasts long enough—and travels far enough through prices and demand—to invalidate the assumptions connecting a company's budget, liquidity and financing.

The transaction does not close when one workstream is ready. It closes when regulatory permission, available funds, currency execution and operational readiness can meet on the same date.

Generative AI is making investment information easier to obtain. It is not making the consequences of an investment decision easier to carry.

A sale-and-leaseback releases capital once and repurchases occupancy over time. The transaction works only when the use of proceeds is stronger than the burden, constraints and risks retained in the lease.

Euroclear’s move from 49% to 90% ownership of Inversis combines European scale with a strong local franchise. The strategic value will depend on whether the two can be integrated without turning operational complexity into client friction.

A strong teaser does not try to tell the whole story. It gives the right buyer enough evidence to recognise relevance, while preserving the seller’s control over what is disclosed, to whom and when.

The policy rate matters. But companies do not borrow from a headline. They borrow through markets and institutions that reprice risk, maturity, collateral, optionality and execution in different ways.

Debt, minority equity and a strategic sale do not merely carry different prices. They allocate different rights, obligations and futures. A useful comparison begins with what shareholders want to control when the transaction is over.

Extending maturity can remove an immediate funding cliff. It does not, by itself, create cash generation, reduce principal or restore debt capacity. Boards should know which problem they are actually solving.

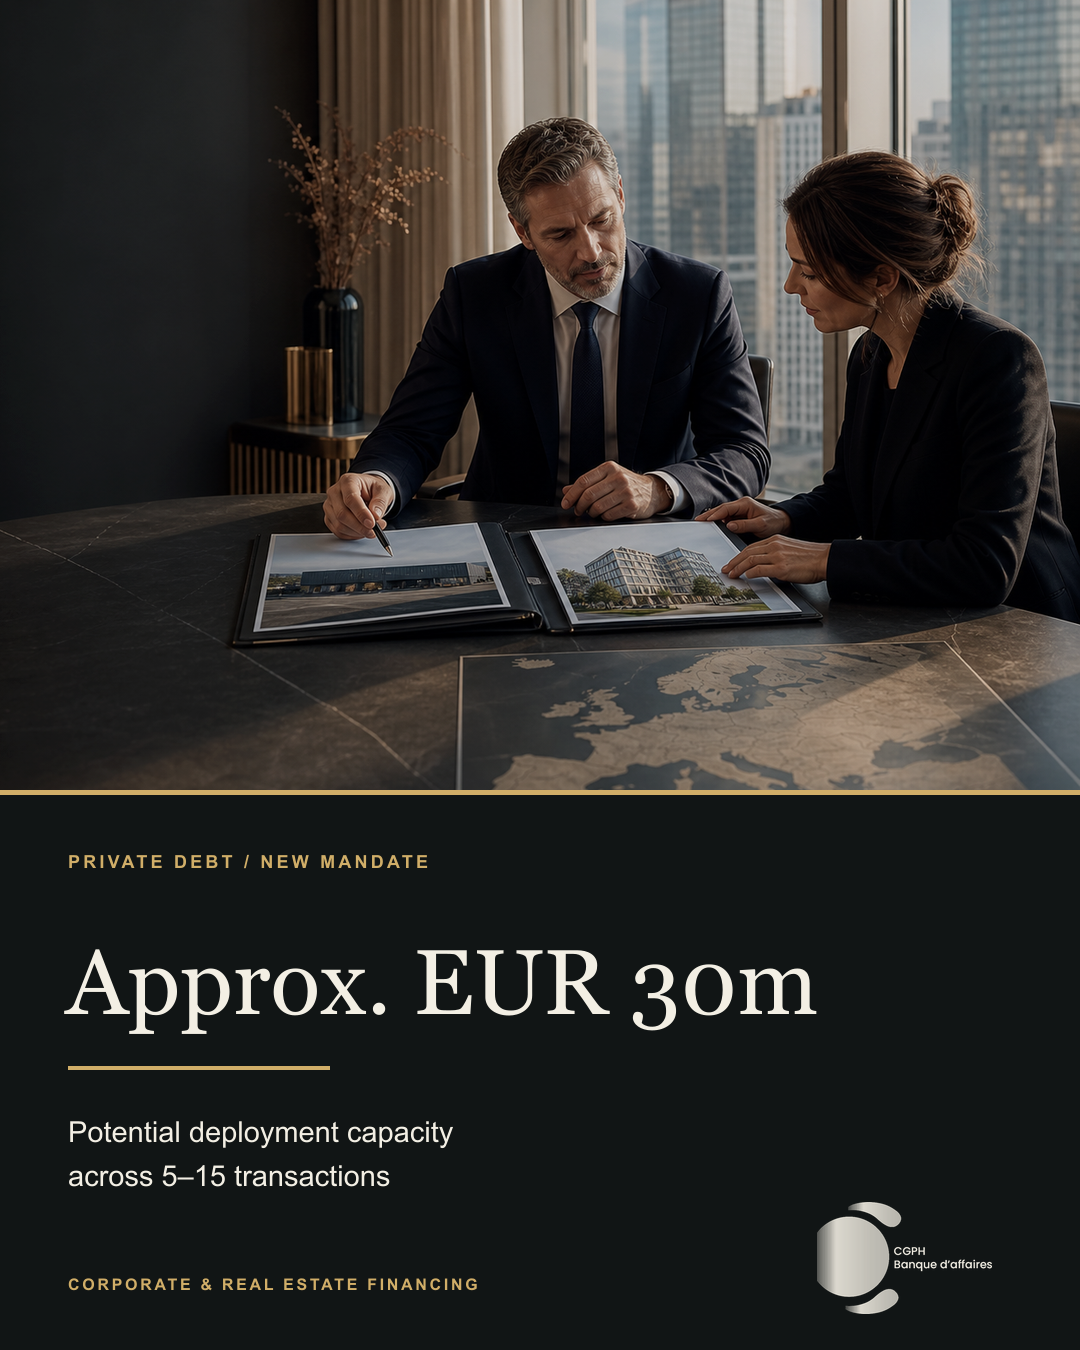
CGPH Banque d’affaires has received a new private-debt origination mandate targeting approximately EUR 30 million across 5–15 corporate and real-estate transactions over the next twelve months in the United Kingdom and Western Europe.

A share offer with a capped cash alternative is not simply a way to settle the price. It decides who retains market exposure, who absorbs financing risk and how much flexibility survives between announcement and completion.

Europe is making it easier to understand how a material bank transaction will be assessed. That does not make consolidation simple. It makes the strategic case easier to test.

When the US Treasury buys back its own bonds, the superficial comparison is quantitative easing. The useful analysis begins where that comparison ends.

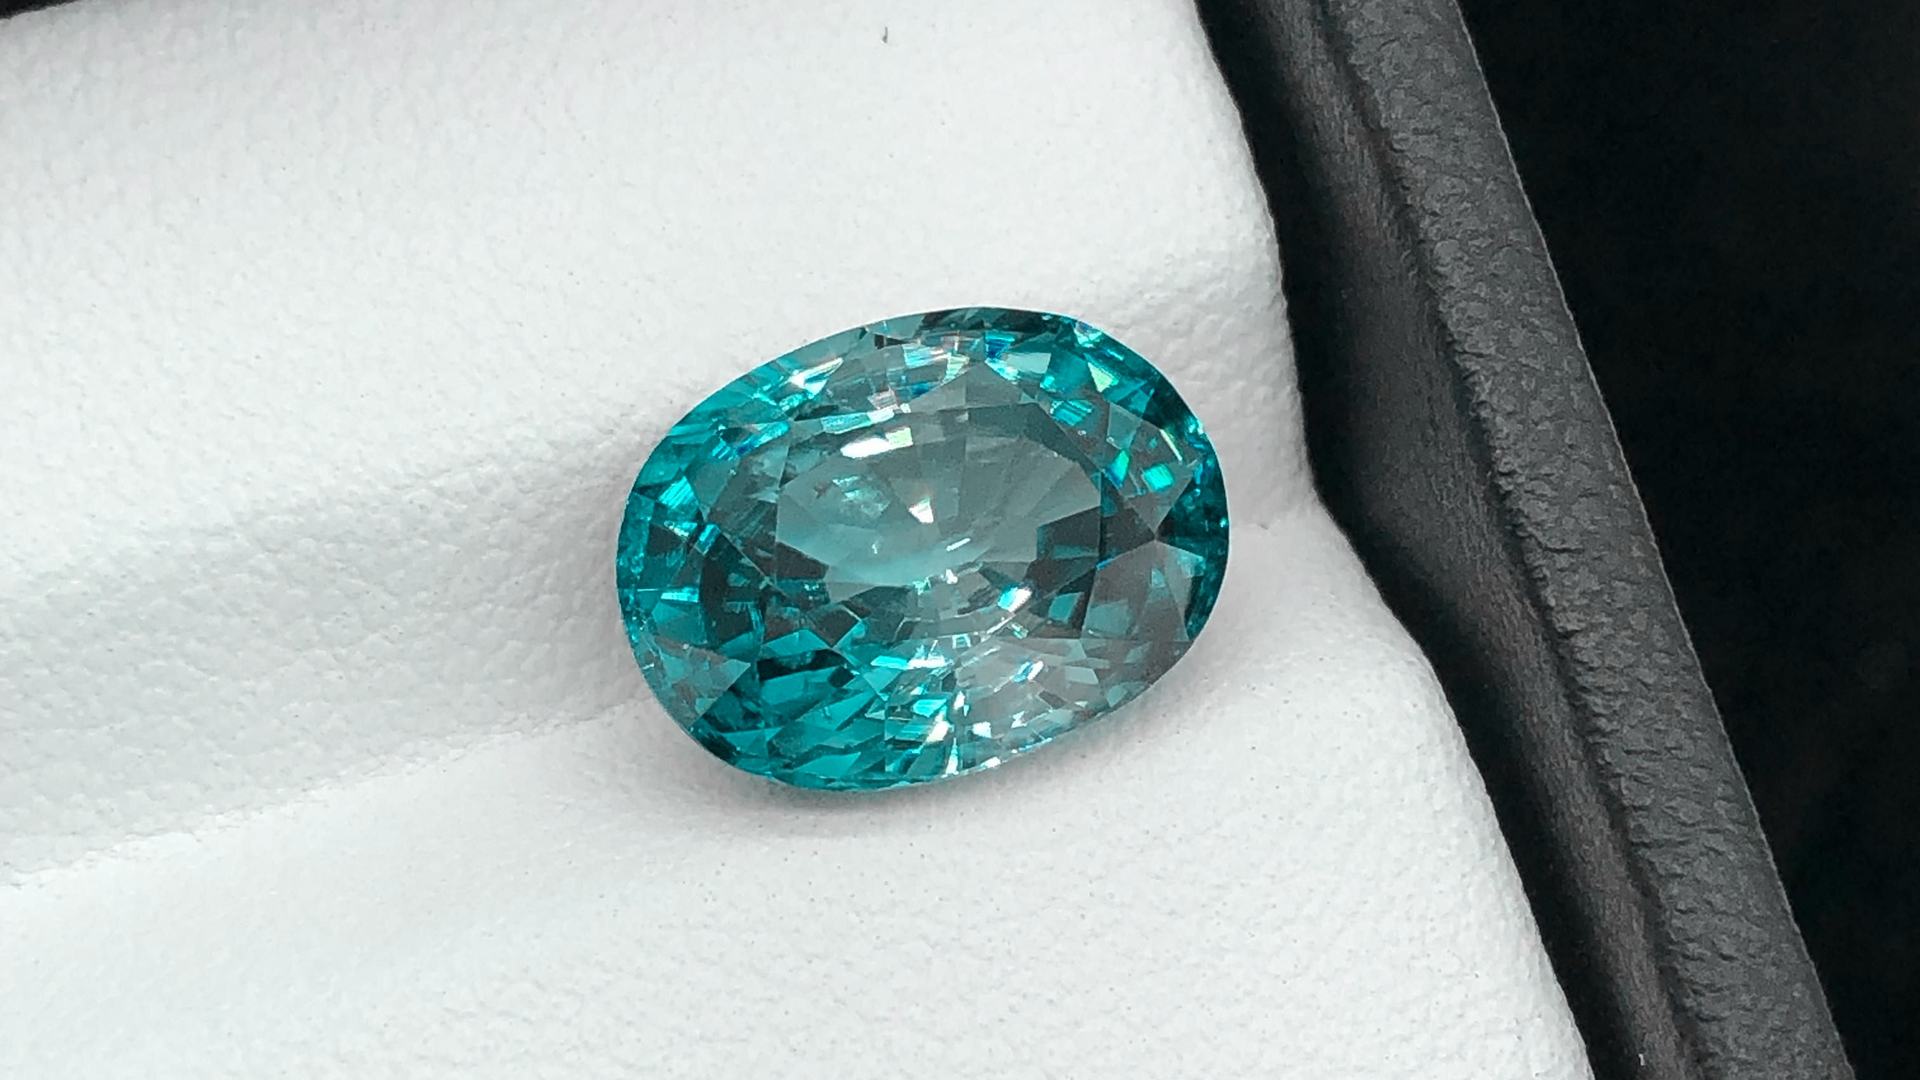
Can tokenization unlock the world's rarest gem? Discover how blockchain fractionalizes Paraíba tourmaline.

A family-owned food production business in Southern Italy faced an uncertain future after insolvency proceedings placed nearly €20 million in assets up for auction. Through collaboration with a U.S.-based investment fund, CGPH Banque d’affaires structured financing of up to €5 million to help the next generation of entrepreneurs pursue the reacquisition of these strategic assets and build a sustainable future for the business.

Elysium founder Tony Parise joins Alberto Chiesa to discuss the evolution of the luxury watch market, the most sought-after models in 2026, emerging opportunities for collectors, and the trends shaping watches as an alternative investment asset.

CGPH Banque d’affaires has surpassed €100 million in financing approvals and pre-approvals within 15 days, reflecting the effectiveness of its institutional funding network, strong execution capabilities and expanding opportunities across financing and advisory activities.

Altherum's official launch event, hosted aboard the private yacht Zaffiro moored at Port Hercule, Monaco. An invitation-only evening for HNWIs, investors, wealth managers and private bankers, centred on a live tokenized sale of curated art and collectible pieces at a pre-defined floor price. A share of the proceeds was donated to Fondazione Francesca Rava. Covered by Milano Finanza's Class CNBC.

CGPH Banque d’affaires attended the Goodwill Ambassadors Award Gala 2026, hosted by the Monaco Ambassadors Club at the Hôtel de Paris in Monaco, an invitation-only evening bringing together diplomats, cultural figures and institutional partners.

CGPH attended the 5th edition of the Monaco International Investment Forum at the Yacht Club de Monaco, engaging with institutional investors, family offices and industry peers. A key session, 'Family Office Investing: Creating Value Across Generations', explored how family offices deploy patient, multigenerational capital.

CGPH Banque d’affaires took part in the 0100 DACH Conference in Vienna, one of Europe's leading private equity and private debt events. Kolyo Boichev, CEO of CGPH Group, spoke on the Private Debt panel, joined by Andrea Battista, Head of Legal, and Alberto Chiesa. Discussions focused on the evolution of private debt markets, the role of institutional capital and structured financing solutions for European companies.
CGPH Banque d’affaires attended IPEM Cannes 2026, one of the leading international events for private equity, private debt and institutional capital. Andrea Battista represented the group alongside Valentina Todorova and Alessandro Montefiori, engaging with global investment funds, family offices and private capital operators.
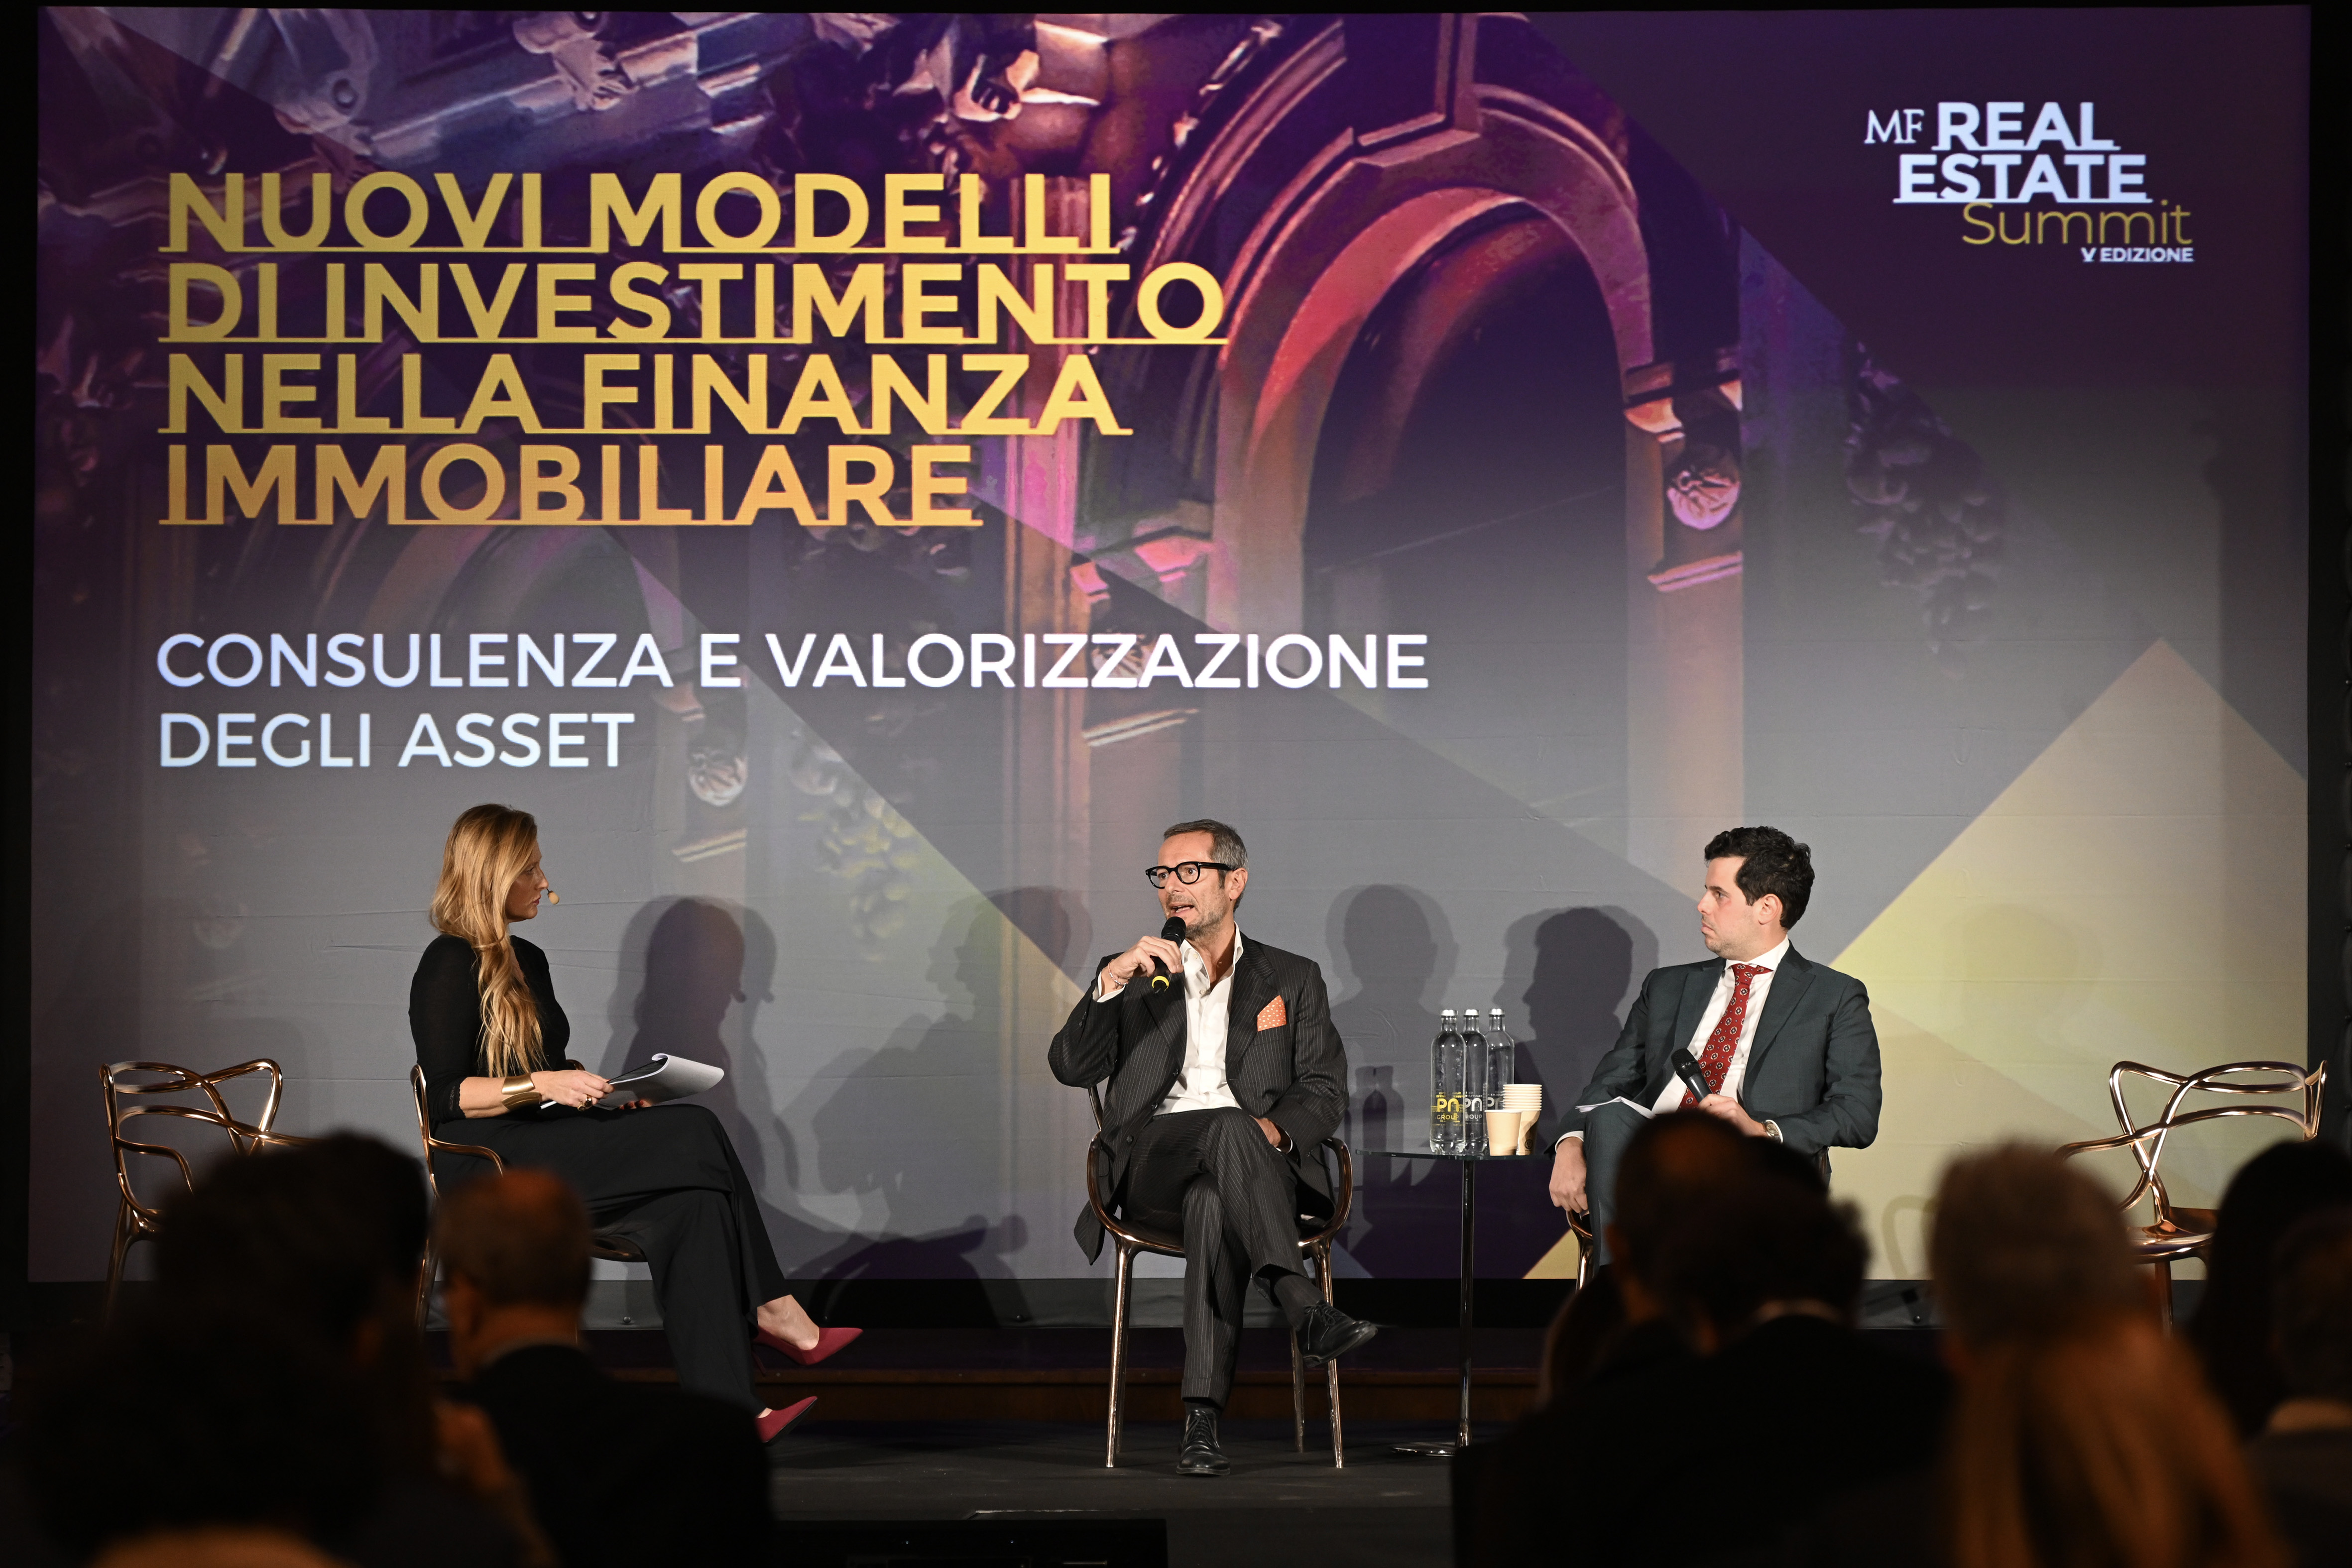
Panel replay from MF Real Estate Summit 2024 — negotiation, finalisation and risk-mitigation strategies in real-estate transactions.

Federico Lione took part in the MF Real Estate Summit 2024 organised by Milano Finanza, contributing to the panel on negotiation, finalisation and risk-mitigation strategies in real-estate transactions.

An introduction to tokenization and its impact on art investing, presented by the Altherum team.

A short editorial video exploring how tokenized art compares with traditional markets.

A short editorial video on €110 million of grants and subsidised financing available to tourism businesses in Italy.

Salone del Risparmio panel — challenges and opportunities in the tokenization of real assets, featuring the Altherum team.

Class CNBC special report from Monaco on Altherum and the new frontier of alternative investments.

CGPH Banque d’affaires at the Goodwill Ambassadors Award Gala 2026 in Monaco.

Chinese Business Club members event in Paris — with Louis Sarkozy and CGPH Banque d’affaires.

CGPH Banque d’affaires at the Chinese Business Club in Paris — with Yannick Bolloré.

How direct capital allocation unlocks value in real assets, beyond traditional fund structures.

An institutional overview of CGPH Proprietary Private Bonds — advisory framing and eligibility perimeter.

A strategic guide by Andrea Battista, Head of Legal at CGPH Banque d’affaires, on how structure and credibility transform ideas into capital. Credibility is the first capital investors buy.

The Altherum team took part in a Salone del Risparmio panel on the challenges and opportunities of tokenizing real assets.

CGPH Banque d’affaires was represented at the 0100 Europe 2026 Conference in Amsterdam by Isabella Virginia Perin, Investor Relations Specialist, and Alessandro Montefiori, Investment & Business Development Analyst, engaging with investors and market operators on private markets and investor relations.

CGPH Banque d’affaires has taken part in MIPIM in Cannes, the world's leading real-estate event, meeting international investors, developers and institutional partners active in real-asset finance.