A Cross-Border Acquisition Has Four Clocks: Regulatory Approval, Financing, FX and Integration
The transaction does not close when one workstream is ready. It closes when regulatory permission, available funds, currency execution and operational readiness can meet on the same date.
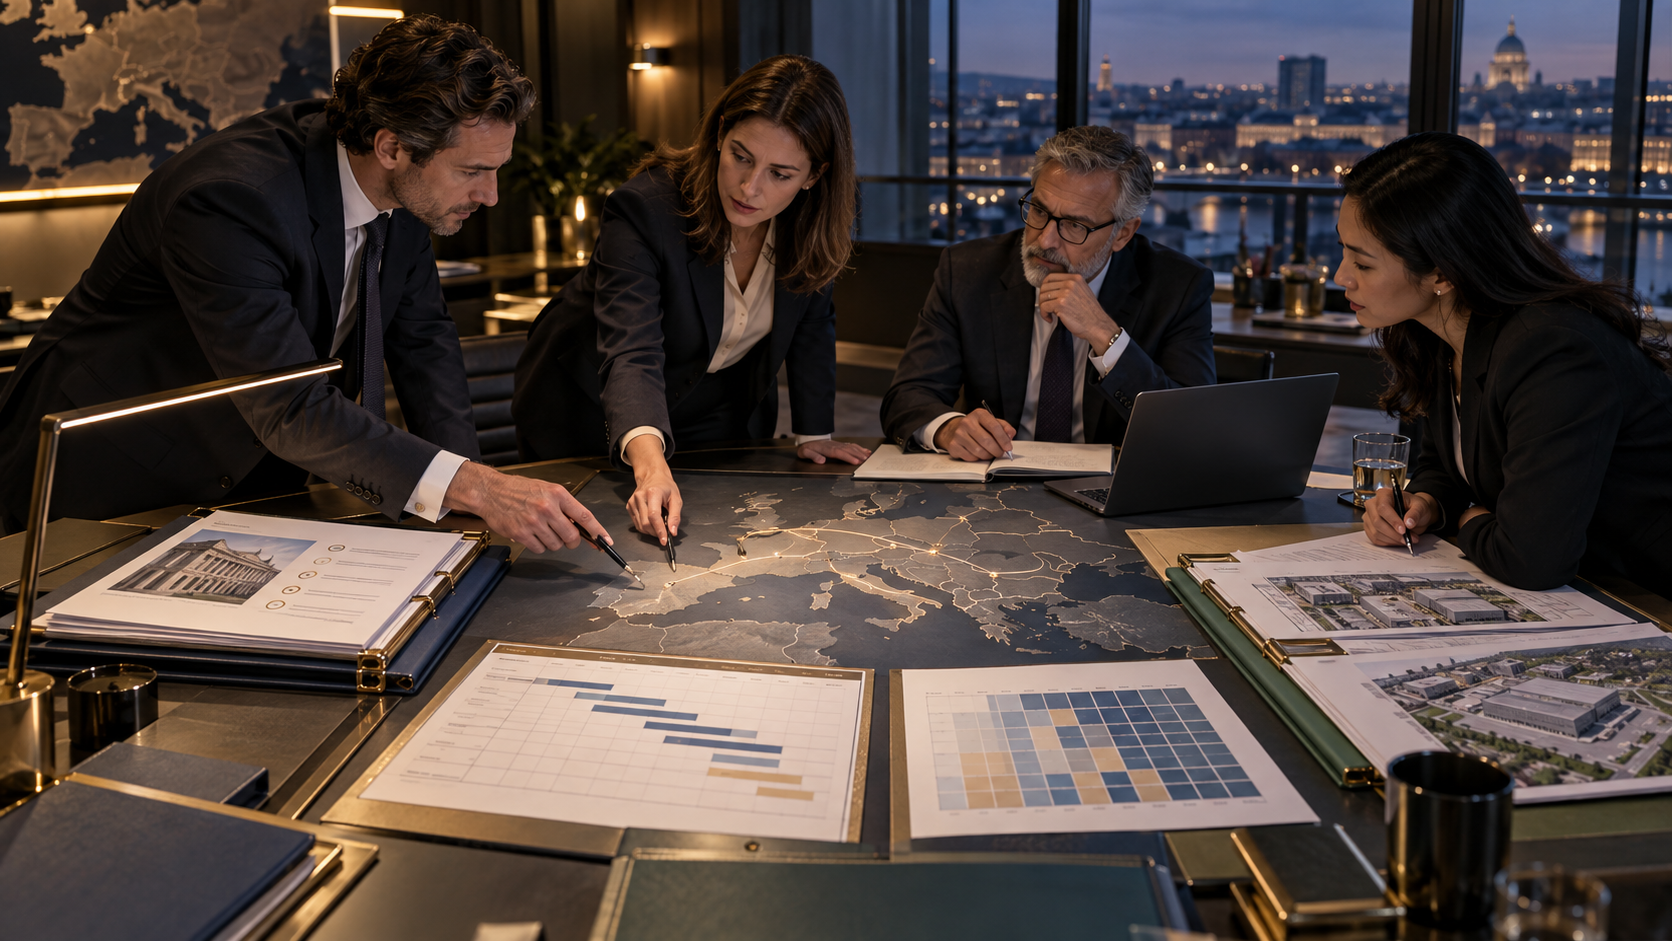
The transaction does not close when one workstream is ready. It closes when regulatory permission, available funds, currency execution and operational readiness can meet on the same date.
A cross-border acquisition may have a clear strategic thesis, an agreed price and committed senior teams. It can still lose value between signing and closing.
One authority asks for more information. A financing condition is tied to a longstop date drafted on a different assumption. The purchase price is fixed in one currency while the buyer’s funding and reporting are in another. Integration teams prepare for day one, but some information or coordination cannot lawfully cross the pre-closing boundary.
Each workstream may be competently managed. The transaction can nevertheless be fragile because the four clocks do not agree.
The board’s task is not to accelerate every clock at any cost. It is to identify the dependencies, decide which risks can be controlled and make sure that the slowest clock does not invalidate the others.
Signing starts the critical path; it does not end the deal
The public narrative of an acquisition often moves from announcement to completion as though the interval were administrative. In reality, signing creates a portfolio of conditional obligations.
The buyer may need merger-control, foreign-investment, national-security or sector approvals. Financing commitments may have conditions, expiry dates and drawdown mechanics. Currency exposure can change while those processes run. The target must continue operating independently until control lawfully transfers, even as both sides prepare for the first day after closing.
The relevant measure is therefore not the duration of each track in isolation. It is the combined critical path.
A regulatory extension may increase hedge cost or move exposure beyond the tenor initially chosen. A financing longstop may arrive before the realistic clearance date. A delayed close may make budgets, synergy assumptions or integration leaders obsolete. A change in transaction structure made to satisfy one authority may alter financing needs, tax analysis or the operating perimeter that integration teams prepared for.
The board should see those consequences before signing, not discover them one function at a time.
Clock one: regulatory approval is a jurisdiction map, not a single filing
Cross-border transactions can trigger several review systems with different tests, information requirements and timetables. Merger control asks competition questions. Foreign-investment and national-security regimes examine different risks. Regulated sectors may require separate change-of-control consent. Local rules can attach to the target’s activities, assets, customers, technology, licences or ownership chain rather than simply to its place of incorporation.
For concentrations with an EU dimension, the European Commission states that notification is mandatory and that the concentration cannot be implemented before notification or a decision declaring it compatible. That rule does not mean every European cross-border acquisition goes to Brussels. It illustrates why jurisdiction and threshold analysis must begin early.
The map is also changing. In June 2026, the European Commission announced updated EU foreign-investment-screening rules with broader coverage, mandatory screening mechanisms in all Member States and minimum procedural requirements, alongside an 18-month implementation period for Member States. National mechanisms and procedures may therefore not be uniform during the transition, which must be tracked country by country rather than treated as one EU filing replacing national analysis.
The UK provides another example. Its National Security and Investment guidance identifies defined sensitive areas in which qualifying acquisitions may require mandatory notification and approval before completion. The consequences and thresholds are specific to that regime; they should not be copied into another jurisdiction’s analysis.
The OECD has documented a further complication: authorities reviewing the same cross-border transaction may differ in procedure and analysis and can reach different decisions. One timetable does not reliably predict another.
Before signing, the board should receive a regulatory route map that distinguishes:
- confirmed filings from possible or voluntary ones;
- acceptance of a notification from substantive clearance;
- statutory review periods from practical time needed to prepare complete information;
- approvals that suspend closing from processes that can continue after it;
- remedies or conditions that could change the transaction perimeter or economics.
A date range without those distinctions is not a closing plan.
Clock two: financing must remain available on the day permission arrives
Financing is often described as “committed” before the workstream has been connected to the regulatory timetable and the closing mechanics.
The useful questions are more specific. When do commitments expire? Which conditions must be satisfied to draw? Can the structure accommodate a delayed closing, a remedy, an excluded asset or a change in acquisition perimeter? When do fees begin to accrue? Which elements depend on syndication, collateral, local security or funds flowing through several jurisdictions? What happens if clearance arrives near the end of the availability period?
The acquisition model should distinguish sources and uses at signing, at the expected close and at a delayed close. It should include transaction costs, refinancing of target debt where applicable, working-capital needs, minimum cash, taxes where relevant and any remedy-related separation cost. It should also identify which amounts are estimates and which are contractually fixed.
The board does not need every financing document in its main paper. It does need a clear view of conditions, flex, expiry and the party that owns each unresolved item.
Financing resilience is not the same as maximising leverage. The question is whether funds remain sufficient and executable across the same scenarios used for regulatory timing and operating performance.
Clock three: FX exposure begins before the asset belongs to the buyer
When the purchase price, funding currency, target cash flows and buyer reporting currency differ, the transaction contains several currency exposures—not one.
The first is the purchase-price exposure between signing and payment. A price fixed in the target currency can become more or less expensive in the buyer’s currency while approvals are pending. The second is funding exposure: debt may be drawn in a currency that does not match the purchase price or the target’s future cash generation. The third is the post-closing translation and operating exposure created by the acquired business.
These risks have different horizons and cannot be solved by one headline hedge ratio.
The decision should begin with a timeline: when the obligation becomes sufficiently certain, which events can delay or cancel it, when cash must be delivered and which currencies will service the resulting capital structure. Then test the economics under the expected close, a delayed close, a reduced perimeter and a failed transaction.
Hedging can reduce selected currency uncertainty; it does not remove transaction risk. If closing is delayed or does not occur, the hedge may need to be extended, unwound or replaced. Instruments introduce counterparty, liquidity, operational and legal considerations of their own. The BIS identifies these as distinct risks across the lifecycle of FX transactions, although its guidance is directed to banks rather than corporate acquirers.
The board should therefore approve an exposure policy and decision authority, not a speculative currency view. Execution belongs with the relevant authorised financial institutions and the company’s treasury and advisers.
Clock four: integration must be ready before closing but remain on the correct side of it
Integration has an apparent paradox. If planning starts only after closing, the buyer loses time and may disappoint employees, customers and suppliers. If the parties begin behaving as one business too early, they may cross legal or regulatory boundaries and weaken the target’s independent decision-making before control transfers.
The solution is not to stop planning. It is to design the planning perimeter.
Integration work should distinguish three categories:
Ready before closing: leadership hypotheses, governance design, day-one communications, control and reporting requirements, operational-risk priorities, technology and data dependencies, and a sequenced decision list.
Prepared through safeguards: competitively or commercially sensitive information that may require clean teams, external advisers, aggregation, redaction or controlled access under qualified legal guidance.
Executed only after control transfers: changes to pricing, customers, suppliers, employees, systems, commercial strategy or other conduct that the parties cannot lawfully coordinate before closing.
The exact line is jurisdiction- and fact-specific. It must be set by qualified legal and regulatory advisers. Strategically, however, the board should insist on one named owner for the boundary and one decision log for exceptions.
Integration readiness should also be tested against possible remedies. If a business line, contract, licence or geography is excluded, which synergies survive? Which systems, people and data still move? Does the financing case remain valid? A plan built only for the signing perimeter is not ready for a conditional clearance.
The clocks interact through six failure points
Most execution risk appears at the interfaces rather than inside a single workstream.
Longstop mismatch. The regulatory downside case extends beyond the financing availability period, hedge tenor or contractual longstop.
Perimeter mismatch. A remedy, carve-out or approval condition changes the assets, earnings, cash needs, synergy assumptions or integration scope, but other models still use the original transaction perimeter.
Currency mismatch. Purchase price, debt service and target cash generation are modelled separately, leaving the combined FX exposure unclear.
Information mismatch. Financing, regulatory and integration teams use different datasets, definitions or update dates.
Authority mismatch. No one knows who can extend a hedge, accept a remedy, change financing or revise the integration plan within agreed limits.
Day-one mismatch. The legal close is treated as operational readiness even though access, banking, reporting, licences, people or systems are not ready to function safely.
These are governance failures as much as technical failures. Each should have an owner, trigger, escalation route and decision deadline.
One dashboard, four clocks
A board-level signing-to-closing dashboard should be concise enough to use and detailed enough to expose dependencies. For each clock, it should show:
- the next decision or deliverable;
- the base, downside and outside timing case;
- the assumptions shared with another workstream and the date on which they were last verified;
- the financial or strategic consequence of delay;
- the person authorised to act;
- the point at which the transaction structure or board approval must be revisited.
The dashboard should then include a single integrated closing forecast. That forecast is not the average of four optimistic dates. It is the earliest credible date on which all closing conditions, funds, currency execution and minimum operational readiness can coexist.
The board should also know which clock cannot be accelerated. More advisers cannot force an authority to decide. A longer financing commitment cannot resolve a flawed information package. A hedge cannot rescue a weak acquisition thesis. An integration plan cannot assume control before the company has it.
The slowest clock prices the deal
Price is negotiated at signing, but execution risk continues to change its effective economics. Delay can increase fees, extend currency exposure, consume management attention, alter target performance and compress the time available to deliver the original plan. A remedy can change the asset being acquired. A financing extension can preserve certainty at a cost. A hurried integration can destroy value that the acquisition model assumed.
None of those outcomes is inevitable. They become more likely when the four clocks are managed as separate specialist projects.
CGPH Banque may act as strategic and financial adviser on cross-border growth and transaction analysis within an agreed mandate, including coordination of the integrated decision framework. Legal, tax, accounting, regulatory, company-secretarial, technical and local implementation work remains with the responsible qualified professionals. Financing provision, underwriting, FX execution and other regulated activities remain with the relevant authorised institutions and parties. Clearance, financing, exchange rates, transaction timing and completion cannot be assured.
The objective is not to make every clock run faster. It is to prevent one clock from making the others irrelevant.
References and further reading
- European Commission, Mergers procedures
- European Commission, EU strengthens its foreign investment screening framework, 26 June 2026
- UK Government, National Security and Investment Act guidance on acquisitions, updated 15 July 2026
- OECD, Challenges and sources of divergence in cross-border merger review, 25 October 2024
- Bank for International Settlements, Foreign exchange risks, 1 January 2026
This article is provided for general information only. It does not constitute investment, transaction, financing, foreign-exchange, legal, tax, accounting or regulatory advice, a recommendation, an offer or a solicitation. Regulatory, financing, currency and integration outcomes depend on the transaction, jurisdictions, documents, counterparties and market conditions. Decisions should be taken with the relevant qualified or authorised advisers.